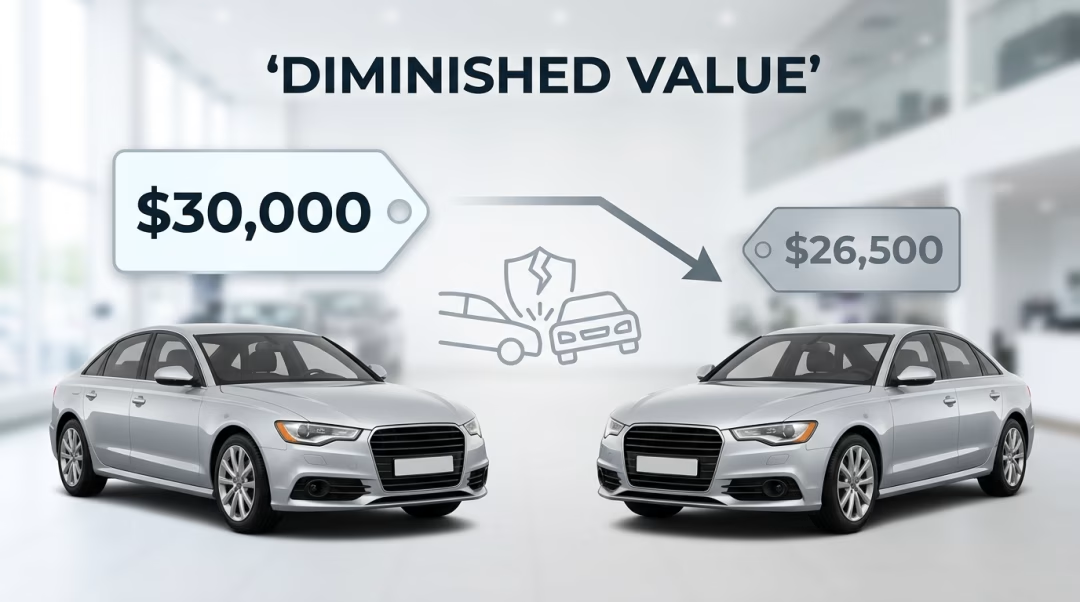
Even after your vehicle has been expertly repaired following an accident, its market value has likely taken a hit. This reduction in resale value is known as "diminished value." It is the perceived loss in value because the vehicle now has an accident history, a fact that will show up on vehicle history reports. Potential buyers are often hesitant to pay the full market price for a car that has been in a collision, regardless of the quality of the repair. A diminished value claim is a way to recover this financial loss from the at-fault party's insurance company. It is a separate claim from the property damage claim that covers the cost of repairs. Understanding how to navigate this process can help you recoup the money your vehicle has lost, ensuring you are made whole after an accident you did not cause.
Filing a diminished value claim requires understanding your rights, gathering the right evidence, and proving your vehicle’s loss in worth. While the insurance company of the at-fault driver is responsible for this loss, they may not offer it voluntarily. Being proactive and knowledgeable is key to a successful claim. This guide will walk you through the essential steps and concepts, empowering you to protect your automotive investment after a collision and make informed decisions, whether you plan to keep, sell, or trade in your vehicle.
When your car is involved in an accident, your immediate focus is on getting it repaired. You take it to a reputable shop, the work is done to perfection, and it looks and drives just like it did before the incident. However, a permanent blemish now exists on its record. This "accident history" is what causes diminished value, and it is a real, tangible financial loss. Navigating the world of insurance claims to recover this loss can be complex, but with the right information, you can protect your asset's value.
Diminished value is not a single, one-size-fits-all concept. It is generally broken down into three distinct categories, each representing a different aspect of the value loss your vehicle experiences.
For most drivers seeking compensation, the focus will be on Inherent Diminished Value, as it is the most predictable and widely accepted form of loss.
Eligibility is a critical first step. In almost all jurisdictions, including Kentucky, you can only file a diminished value claim if you were not the at-fault driver in the accident. The claim is made against the at-fault party's property damage liability insurance. You cannot file this type of claim against your own insurance policy, even if you have collision coverage, as those policies are designed to cover the cost of repairs, not the subsequent loss in market value. If the at-fault driver is uninsured or underinsured, you may be able to file a claim under your own Uninsured/Underinsured Motorist Property Damage (UMPD) coverage, if you carry it.
Proving diminished value is the claimant's responsibility. The at-fault driver's insurance company will not do the work for you and will often try to minimize or deny the claim altogether. A strong claim requires solid evidence and a credible calculation of the loss.
Some insurance companies use a formula known as "Rule 17c," which originated from a Georgia court case. This formula starts with a 10% cap on the vehicle's pre-accident value and then applies multipliers for damage severity and mileage. However, this formula is widely criticized by consumer advocates and appraisal experts for producing artificially low valuations that benefit the insurance company. It does not account for market conditions, vehicle type, or the specific nature of the damage.
The most effective way to prove your claim is to hire an independent, licensed auto appraiser who specializes in diminished value. An expert appraiser will conduct a thorough inspection of the repaired vehicle, review all repair documentation, and analyze real-world market data for comparable vehicles. They will then produce a detailed report that provides a credible, defensible valuation of your loss. This professional report carries significant weight in negotiations with an insurance adjuster and is essential if you need to take the matter to court.
Filing a successful claim involves a clear, methodical process. Follow these steps to maximize your chances of recovering the value your vehicle has lost.
Understanding this process is not just for recovering lost money; it is also vital when you are looking to purchase a pre-owned car from our extensive inventory or considering your options for getting pre-approved for a newer vehicle. A car with a history of significant repairs, even if not immediately obvious, can have underlying issues. That is why knowing how to spot structural damage is a crucial skill for any savvy car buyer.
No, you typically cannot. Diminished value claims are filed against the at-fault driver's property damage liability insurance. Your own collision policy is designed to pay for the cost of repairs to restore your vehicle to its pre-accident condition, but it does not cover the loss of market value.
In Kentucky, the statute of limitations for property damage, which includes diminished value, is typically two years from the date of the accident. It is always best to start the process as soon as the repairs on your vehicle are complete to ensure you do not miss this deadline.
While not legally required, it is highly recommended. An insurance company is unlikely to take your personal opinion of the value loss seriously. A detailed report from an independent, certified appraiser provides unbiased, third-party evidence that is difficult for an adjuster to dispute and is essential for building a strong case.
Filing a claim against another driver's insurance policy should not affect your own insurance rates. You are making a claim as a third party against a policy you do not pay for. Your rates are typically only affected when you file a claim against your own policy for an accident in which you were at fault.
To build a strong case, you should gather the official police report, the other driver's insurance information, the final itemized repair bill from the body shop, photos of the damage before and after repairs, and the professional diminished value appraisal report. Having this documentation organized will make the process much smoother.